EPISODE 007 · CORPORATE FINANCE → ENTREPRENEURSHIP
Melissa K. Diaz on what a startup actually needs financially, and in what order
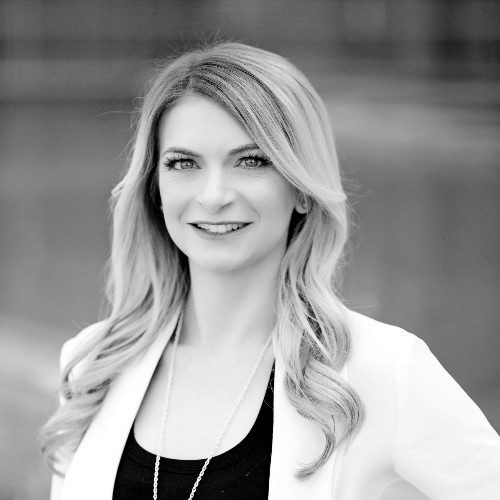
Melissa K. Diaz is a CPA who left corporate finance at a Fortune 500 hotel company and built an accounting firm from nothing. This episode is deliberately practical. If you are starting a business, what do you actually need financially, in what order, and what can wait? Her first answer is the one nobody expects from a CPA: do not hire a CPA yet.
What you will learn
- The red flag that means leave. If you cannot innovate and you are on a hamster wheel, the only thing seniority buys you is more work.
- Do your own books first. Set up QuickBooks or Xero yourself and connect a bank feed. Paying a firm to do it costs you money you could have spent on advice.
- Build the company with the exit in mind from day one. The advice changes completely depending on whether you want an IPO or a cash flow business.
- One question tells you whether to raise. Would you take a second mortgage to grow this?
- The ten year old test. If an average ten to thirteen year old understands your business model, you are ready for investors.
- A $40,000 lesson in employment law. Why fractional help is the lower risk option when you are small.
Why did she leave corporate finance?
Because she kept suggesting better ways of doing things and kept being looked at as though she had grown a second head. She started in audit at RSM, a global accounting firm, where the standing instruction was to do it the same way it was done last year. Then she went to Starwood, the Fortune 500 hotel company, which is supposed to be the pinnacle, and found more of the same. So many people sat in so many processes that a single small change had to travel through four or five approvals before it existed.
She is careful to say there are reasons for those controls. Her objection is what they cost.
“It stole a lot of the curiosity. If we can't innovate and we can't do something new, then the only benefit that comes from staying with a company like that is that you get more work as you move up.”
Melissa K. Diaz, Women IN episode 7
Her advice to anyone recognizing themselves in that is blunt. Feeling stuck on a hamster wheel with no room to move forward is a red flag, not a phase. It is the signal to start asking what you actually want to do.
What she did was call a friend from her RSM days who had a crazy idea: build an accounting firm an entirely different way, on a foundation of efficient and innovative service. That became High Rock Accounting, built on two commitments. Give accountants a better life than standard corporate gives them, and bring enough technology into the work that the product itself is better.
What should a brand new business do financially, first?
Foundational documents, in this order. Your EIN. Your articles of incorporation. Your state registration with the corporation commission. Employment accounts, if you are going to have employees.
Then the part founders do not expect to hear from an accountant. Set up a simple QuickBooks Online or Xero account yourself, and integrate a bank feed. You do not need to know accounting and you do not need to start coding transactions. You just need the general ledger to exist and the data to be flowing into it.
“You actually don't really need us to do that. We will. You'll pay us a lot of money to do it. You can save that money. Do it yourself.”
Melissa K. Diaz, Women IN episode 7
Her estimate is that walking in with books already set up buys you two or three meetings with a CPA that you would otherwise have burned on data entry.
Why does the exit matter on day one?
Because an advisor cannot help you until they know where you are going. Raising capital and aiming at an IPO builds one company. A cash flow business that funds a nice life builds a completely different one. Melissa can advise either, and the advice is not the same.
The pattern she keeps meeting is a founder who arrives asking for help, gets asked whether they want to scale, be acquired, or take on partners, and answers: I don't know, I just set up a website. That is the problem her firm is trying to solve with a product they call Business in a Box, launched first for RUO peptide resellers and intended to expand into other industries. The point of it is to get the foundational decisions made in one place, early, before a blind spot turns into something expensive.
How do you know whether to raise money?
This is the cleanest piece of advice in the episode, and it fits in one question. Would you take a second mortgage on your home, or a loan against your 401k, or personal debt, to grow this company?
If the answer is no, stop deliberating and start getting in front of investors now, because even a phenomenal idea can take years to fund and there is no way to predict how investors will react until you are in the room. If the answer is yes, do not raise. Bootstrapping to success while keeping all of your ownership is, in her words, the absolute ideal. And if you later decide you do want outside money, arriving with traction changes the terms. In tech the benchmark she cites is ten thousand dollars a month in recurring revenue, which is roughly where real investor interest begins.
There is a corollary about how you explain the business, and it is the best line of the hour. Find an average ten to thirteen year old, ideally one with no interest in business, out riding a bike. If they understand your model, you are ready to explain it to adult investors.
“The faster and more clearly you can effectively express your idea, the faster and more quickly you will get investment.”
Melissa K. Diaz, Women IN episode 7
Fractional help or employees?
Melissa is a fractional service provider and says so before she argues for them, which is the right way round. Her case has two parts.
The first is risk. A contract can be ended. Most fractional providers work month to month or on short terms, so if the work is wrong or you simply do not communicate well, you stop. An employee is covered by employment law, which exists for good reasons, and which is expensive to be on the wrong end of. Around 2019 her firm had an erroneous claim made against it. They defended it successfully with the Arizona Department of Labor and it cost forty thousand dollars. They were right, they won, and they ended up exactly where they started, minus the money. For a startup, she points out, a claim that size is fatal, and you cannot ignore it: the department will side with the employee by default.
The second is depth. A generalist CFO can do the work but will not necessarily know what to look for. Her firm specializes in cannabis, which means tracking regulatory change every single week rather than when something breaks. Specialist knowledge is mostly a list of blind spots you already know about.
She will not let the point run away with her, though. Vendor contracts carry their own liability, a bad falling out with a vendor can become just as public as a bad exit, and a contractor agreement deserves the same legal review you would give any other.
So when do you hire actual employees?
Three triggers. When you need control over the schedule and the location, because a contractor can be given a deadline but not a Wednesday in your office. When there is significant proprietary information and you want the stronger legal recourse that comes with employment. And when the hire is strategic, somebody who brings a network, investors or specific industry knowledge, in which case her advice is to move fast. Equity compensation is the lever startups have and service providers rarely take.
What founders get wrong is also two things. The first, which Sondra raises and Melissa immediately agrees with, is hiring into a spike. The overwhelm is real but it is not constant, the role was never defined clearly enough, and three months later the work has dried up. The second is expecting an employee to carry founder level endurance.
“I need to be straightforward in saying that we are a startup. That means I cannot guarantee that what your role is today will be what your role is next month, or maybe in six months.”
Melissa K. Diaz, Women IN episode 7
Her instruction is to be brutally honest at offer stage, because employee one, two and three are going to be standing in the mess with you whether you describe it to them or not.
What does she see women doing differently with money?
Two things, and they pull in opposite directions. In her experience women run their businesses finances better. They also consistently undersell the opportunity.
She has watched male founders pitch companies she does the books for and thought, that is nothing like what you are actually doing, but I can see where you are going. Women do the reverse. They lead with the groundwork, surface every risk they have already solved for, and say they think it is a good opportunity and here is why. It is honest, and it does not raise money, because money responds to the sense that you might miss out.
The fix she offers comes from a book by the jury consultant Karen Lisko, whose exact title she could not remember on the day. Lisko spent years teaching prosecution and defense attorneys how to speak to a jury to get a result, and the lesson Melissa took from it is a grammatical one. Women say, I believe that if we do this, this will be the result. Men say, we need to do this or we will not get that result. The shift is small and it is not about certainty.
“I understand you may still have some doubt in your mind. You don't need to portray that doubt.”
Melissa K. Diaz, Women IN episode 7
The note taker trick
Melissa has spent years in rooms full of numbers and mostly men, and she has a specific, usable tactic for it. Use a note taker. Not for the notes, although the notes are fine. Use it so that you are freed from catching every word, and can spend the meeting watching faces, posture and energy instead.
Her argument is that women have been trained to read a room for so long that it functions as an information advantage, and the advantage only pays if you are not also transcribing. The men in the room, she says plainly, are not doing that. You leave with more than anyone else did.
The other half of operating in those rooms is resilience. She thinks women take criticism harder, and she is not arguing against reflection, which everyone should do. She is arguing against letting feedback become a verdict. Note it, decide whether it changes anything, and if it does not, keep going.
What is the one thing she wants you to do this week?
Find one task, worth at least ten minutes a week, and delegate it away. Her own example that week was training her executive assistant to filter her LinkedIn messages, because thirty messages a day arrive and two of them matter. Ten minutes a day is fifty minutes a week. That is lunch. That is a podcast.
Where to find Melissa K. Diaz
- High Rock Accounting — highrock.co, and highrock.co/contact to reach the firm directly. Information about the Business in a Box course is on the site.
- LinkedIn — Melissa K. Diaz, CPA
Where to listen
Listen to Women IN episode 7 with Melissa K. Diaz wherever you get your podcasts.
Frequently asked questions
Who is Melissa K. Diaz?
Melissa K. Diaz is a CPA and a co-owner and partner at High Rock Accounting, a fractional accounting and CFO firm. She began in audit at RSM, moved to corporate finance at Starwood, a Fortune 500 global hotel company, and then left to build High Rock with a friend from her RSM days. She works across healthcare, hospitality and cannabis, and chairs the finance board for Girls in Tech.
What are the first financial steps a new business should take?
Set up the foundational documents first: your EIN, your articles of incorporation, your state registration with the corporation commission, and employment accounts if you have employees. Then set up a general ledger yourself in QuickBooks Online or Xero and connect a bank feed. Melissa Diaz is explicit that founders should not pay a CPA firm to do this, because doing it yourself saves two or three meetings worth of fees later.
How do you know whether to raise outside capital?
Melissa Diaz uses one gut check. Are you willing to take a second mortgage on your home, a loan against your 401k, or personal debt to grow the company? If you are not, go and seek investment capital now, because it is a long road. If you are, do not seek it: bootstrapping while keeping all of your ownership is the ideal position, and reaching traction first gets you a far better valuation.
When should a startup hire employees instead of fractional help?
When you need control over when and where the work happens, when there is significant proprietary information involved, or when the hire is strategic, for example someone who brings investors or deep industry expertise. Otherwise a fractional contract can be started and stopped month to month, which matters enormously when every dollar counts.
Where can I find Melissa K. Diaz and High Rock Accounting?
High Rock Accounting is at highrock.co, with a contact form at highrock.co/contact. Melissa is on LinkedIn as Melissa K. Diaz, CPA.